Regulatory overview
- Scope
- European Union
- Authorities
- Regulatory index
- Latest regulatory change
 European Union
France applies MiCA to crypto-assets within its scope, with the AMF responsible for providers and the ACPR exercising powers over ART and EMT issuers and payment services. The PSAN transitional regime ended on July 1, 2026. For tokenized securities, the Monetary and Financial Code recognizes distributed ledger entries for securities not admitted to a central securities depository and for securities admitted to a pilot regime DLT infrastructure, subject to conditions distinct from CASP authorization.
Is crypto legal in France?
Yes. Businesses have regulated routes to operate with crypto-assets, under predictable rules. The AMF publishes CASP permissions; the ACPR defines issuers.
In the Metlabs Regulatory Index it scores 100/100 and ranks 1 of 76 countries assessed (assessed October 3, 2026). See the country ranking
France’s digital asset framework combines European crypto-asset regulation with French securities and financial services law. The Markets in Crypto-Assets Regulation, MiCA, applies to certain issuances and services; where a token qualifies as a financial instrument, securities rules become the starting point. A crypto-asset exchange and a company issuing tokenized shares may therefore need different legal structures and permissions even though both use blockchain.
France also recognizes certain securities entries in distributed ledgers. This mechanism must connect with the investor’s rights, the recording system and each participant’s activity. This guide explains the roles of the AMF and ACPR, what replaced the former PSAN regime and what a project should establish before issuing, safeguarding or trading digital assets from France.
How MiCA differs from the securities framework
The MiCA Regulation establishes the EU framework for crypto-asset offerings and services. Tokens that qualify as financial instruments fall outside its scope and follow applicable securities and investment services rules. In France, prestataire de services sur crypto-actifs, or PSCA, corresponds to a MiCA CASP and must be distinguished from the former national PSAN regime, created by the 2019 PACTE Law with mandatory registration for certain services and optional authorization; Law 2023-171 strengthened that registration from 2024.
The AMF confirmed in July 2026 the end of the transition from the PACTE framework. Former PSAN registration or authorization no longer provides a standalone basis for continuing services under MiCA. A pending application must not be described as an obtained authorization. Providers must verify their entitlement. For firms that did not obtain MiCA authorization, the AMF monitors the implementation of orderly wind-down plans, giving priority to protecting clients' interests; those plans may include transferring clients to an authorized PSCA.
What the AMF and ACPR supervise
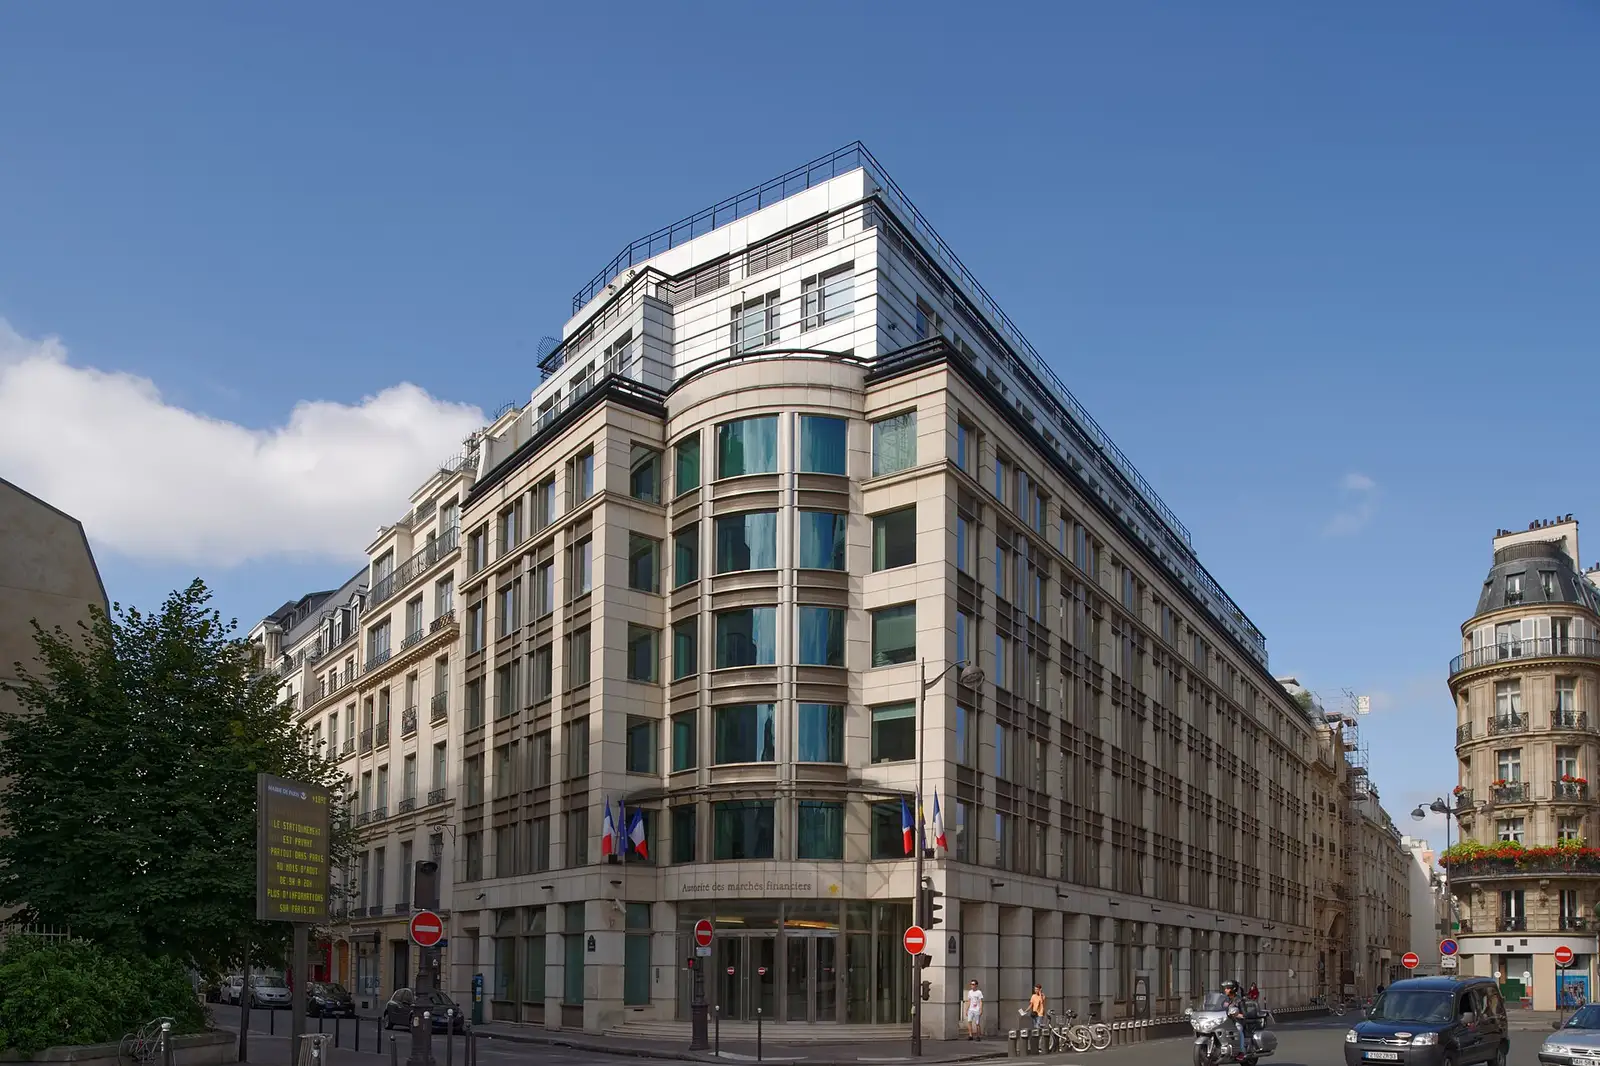
The AMF handles authorization and supervision of PSCA providers and crypto-asset offerings within its remit. The ACPR publishes procedures for both ART and EMT issuers according to the entity and project. Assigning ARTs generally to the AMF and EMTs to the ACPR does not accurately describe the division of responsibilities.
The ACPR also acts where a service constitutes a payment activity. European powers under MiCA must be considered alongside national supervision. Official registers identify the service provider and permitted activities. A platform's trading name or membership in a financial group does not replace that verification.
What authorization a project needs to operate
The first step is to separate issuance, distribution, custody, exchange and payments. Then identify the company contracting with clients and the supervisor responsible for each function. A brand offering all these services may rely on several authorized entities, but its contracts and operational flows must reflect that allocation of responsibilities.
Articles 59 and 60 of MiCA distinguish CASP authorization from notification by certain financial entities. The entitlement must match the services actually provided. The European procedure allows operations in other Member States within its scope, but does not turn crypto-asset permission into authorization to offer financial instruments, manage funds or provide every payment service.
ACPR expectations for EMT services address the interaction between MiCA and PSD2. The authority distinguishes affected custody and transfer services from other payment activities requiring a broader application. It also considers the interaction between European deadlines and providers under the former PSAN transitional regime. A business must determine its particular position rather than assuming one authorization covers all its operations.
How tokenized securities are represented and transferred
Article L.211-3 of the Monetary and Financial Code permits securities to be entered using distributed ledger technology instead of a securities account in the cases set out in Article L.211-7: at the issuer's discretion, securities not admitted to a central securities depository's operations, and securities admitted to a DLT market infrastructure under the pilot regime. It requires safeguards, particularly authentication, at least equivalent to account entries, under the conditions of Article R.211-9-7 (Decree 2018-1226, as amended by Decree 2023-421). Recognition concerns the legal mechanism defined by the legislation, not every record created on a blockchain network.
Article L.211-7, in force since May 2025, distinguishes securities admitted to a central securities depository's operations, securities that are not, and securities admitted to a DLT market infrastructure. For the latter it connects the national framework with Regulation 2022/858. Outside the pilot regime, distributed ledger entries are limited to securities not admitted to a central securities depository's operations, and bringing an issuance to trading requires the corresponding infrastructure. The issuance category and infrastructure must be identified before legal effects are attributed to the records.
The DLT Pilot Regime permits trading and settlement infrastructures subject to specific permissions and exemptions. France already has one such infrastructure authorized, so a trading and settlement route exists, but an infrastructure's authorization does not release issuers or intermediaries from their own duties. For real estate or other property, documentation must specify whether the token represents a security, contractual right or right over the property, together with its transfer and enforcement mechanisms.

Which obligations continue after authorization
PSCA obligations depend on the services provided and include organizational, asset protection, conflicts and conduct requirements. Advice and portfolio management require assessment of client suitability under MiCA. Anti-money laundering controls and transfer information requirements must be integrated into operations, alongside DORA for entities within its scope. Tax rules add a duty to identify customers' tax residence and report information on their transactions to the tax authority, under Article 54 of Finance Law 2025-127 for 2025 (Articles 1649 AC bis to 1649 AC sexies of the General Tax Code) and Decree 2025-1276, which transpose the EU directive on administrative cooperation applicable to crypto-assets (DAC8). It applies to transactions carried out from January 1, 2026, and the first report must be filed by June 15, 2027.
For offerings of crypto-assets other than ARTs and EMTs, white paper notification is not AMF approval. Its contents, risks and rights must match the actual product. Oversight of marketing and external providers is particularly relevant where one platform combines crypto-assets, financial instruments and payment functions.
How to prepare the structure and launch
Preparation begins with holder rights and the markets where the offer will be made. This establishes whether MiCA or financial instrument rules apply, which services each entity will provide and which register will document title. A provider’s permission and an issuance’s compliance are separate assessments that must be resolved before launch.
Lise’s case illustrates how a DLT infrastructure requires coordination across several authorization and supervisory areas: authorization as an investment firm, a DLT multilateral trading facility and a settlement system, with AMF approval of its operating rules. That precedent does not allow another operator to use the framework without securing its own permissions. Technology selection must be accompanied by procedures for recording, settlement, incidents and asset protection.
The file should keep the product, contracts and actual platform operation aligned. Tax, collective investment rules and distribution restrictions require specific assessment where the model triggers them. Current rules must also be distinguished from pre-MiCA preparation documents: their references to the former PSAN framework do not describe today’s entitlement. It is also worth following the Commission proposal COM(2025) 943 of December 4, 2025, which would reform the DLT Pilot Regime and transfer to ESMA the authorization and supervision of crypto-asset service providers, except credit institutions and the financial entities covered by MiCA Article 60. It is a proposal still in the legislative process, not law in force.
To understand how this framework applies to your project, discuss your case with our team.
Key takeaways
- As of July 2026, former PSAN registration no longer replaces MiCA entitlement.
- The ACPR has responsibilities for both ART and EMT issuers; powers are not divided between AMF and ACPR simply by ART versus EMT.
- Articles L.211-3 and L.211-7 define the scope for recording securities using distributed ledgers: securities not admitted to a central securities depository and securities admitted to a pilot regime DLT infrastructure.
- White paper notification is not product approval or a guarantee of returns.
Regulatory milestones
Publication of the shared ledger ordinance
The Official Journal publishes Ordinance 2017-1674 of December 8 on representing and transferring certain securities through shared ledgers. Publication is distinct from subsequent application.
The PACTE Law creates the PSAN regime
Law 2019-486 of May 22 introduces mandatory AMF registration for certain digital asset services and optional authorization. It is the national regime later replaced by MiCA; its registration requirements were strengthened from 2024.
General MiCA application and financial code amendments
General application of the regulation and the cited Article L.211-3 amendments on distributed ledgers begin.
Amended Article L.211-7 applies
The consolidated text incorporates Law 2025-391 amendments concerning securities entries and infrastructure frameworks.
First AMF MiCA authorization: Deblock
The official register dates Deblock’s A2025-001 permission to May 23. The following week, the AMF confirms its first authorization, distinct from the former PSAN registration.
Publication of approval of Lise’s rules
The AMF publishes its decision of October 13 approving the rules of Lise’s DLT multilateral trading facility, which also operates a settlement system under the pilot regime. This infrastructure milestone is distinct from crypto-asset service provider authorization.
ACPR publishes expectations for EMT payment services
The authority explains the interaction of MiCA and PSD2 and the application route limited to EMT payments. The consulted document includes a September 2026 update.
End of the PSAN transitional regime
The former national entitlement ceases to be sufficient for continuing services subject to MiCA.
Get each month's regulatory changes by country
One email a month with the rules approved and taking effect in each jurisdiction, with the official source and the updated guide. You can unsubscribe at any time.
Frequently asked questions
No. PSAN refers to the former French national framework and PSCA to a MiCA crypto-asset service provider. The former entitlement does not automatically become MiCA authorization after the transitional period.
No. It must meet the categories and conditions of the Monetary and Financial Code and, where relevant, the DLT Pilot Regime. The contract, rights and recording system must comply with the applicable framework.
For crypto-assets other than ARTs and EMTs under MiCA Title II, the white paper is notified to the AMF rather than submitted for prior approval. It must meet the required notice period and content rules. Presenting notification as product endorsement would confuse that step with authorization.
It depends on the service. The ACPR identifies EMT transfers on behalf of clients and certain custodial wallets that can send and receive EMTs to and from third parties as payment activities. Where both regimes apply, payment entitlement must be assessed. The streamlined application for services limited to EMTs does not permit every other payment service.
MiCA entitlement allows services within its scope through the Article 65 cross-border procedure. It does not replace permissions needed for financial instruments, funds or payments. The authorized entity, covered services and completion of the procedure must be checked before targeting another market.
How to cite this guide
If you use this guide as a source in an article, academic paper or report, you can cite it as follows (APA style):
Yáñez López, J. (2026, October 15). Crypto-asset regulation and tokenization in France. Metlabs. https://metlabs.io/en/blockchain-regulation/france/